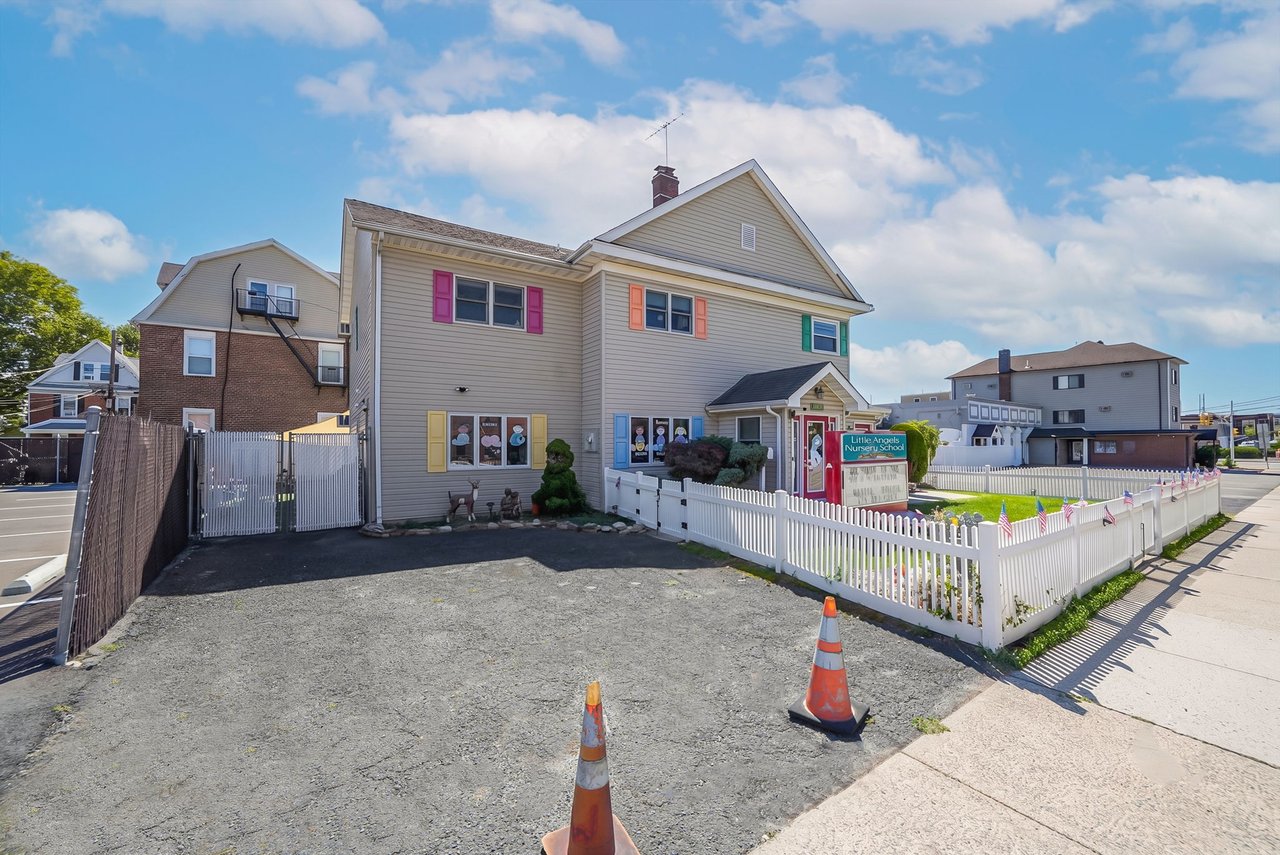
Selling commercial property is a business decision with real consequences. The building may represent decades of work, retirement income, a family investment, or the location where you built your company. Whatever its history, the next buyer will evaluate it through a different lens: income, operating costs, physical condition, financing, and risk.
That is where a successful sale begins. Owners understandably see what they have invested. Buyers see what they can earn, occupy, improve, or eventually resell. Your marketing and pricing strategy must connect those perspectives with evidence.
In Essex County, that requires more than a sign and a few exterior photographs. A storefront in Nutley, a mixed-use building in Belleville, an office property in Livingston, and an industrial building in Newark each demand a different approach. The buyer, underwriting, property story, and potential obstacles change with the asset.
The goal is to sell on terms that make sense for your financial position. That means preparing the property properly, presenting reliable information, reaching qualified prospects, negotiating intelligently, and anticipating the issues that can disrupt a closing. Commercial real estate rewards preparation. Expensive surprises tend to arrive when preparation gets skipped.
Understand the Essex County Market at the Property Level
Essex County contains different commercial environments within a relatively compact area. Municipal boundaries matter, but the useful analysis goes further: the specific street, access, surrounding businesses, customer base, parking, building layout, and permitted uses.
A retail property near complementary businesses may attract an operator who values that immediate customer environment. A warehouse buyer may care more about loading access and truck circulation. An office user may prioritize convenient parking, accessibility, and the cost of adapting the space. Those needs should shape the sale from the beginning.
Newark offers a different setting from suburban communities such as Livingston, Fairfield, Roseland, and West Orange. Nutley, Belleville, Bloomfield, and Montclair contain opportunities that must be evaluated block by block. An attractive town name does not compensate for a property that fails its intended user’s practical requirements.
Transportation deserves particular attention. NJ Transit identifies Newark Broad Street as a station on the Montclair-Boonton and Morris & Essex lines. That connection may be relevant to certain office, service, and investment buyers, but actual station access must be assessed for the individual property. Proximity is a fact to document, not a promise of demand. New Jersey Public Transportation Corporation
The same discipline applies to highways and regional infrastructure. Show buyers how the property connects to their operations. Verify routes, travel considerations, loading conditions, and employee access. Avoid generic claims about being convenient to everything. Commercial buyers want specifics that help them determine whether the building works.
The practical takeaway is straightforward: there is no single Essex County commercial market. There are individual assets competing for particular buyers. A useful valuation studies that competition directly rather than relying on broad headlines or countywide averages.
Decide What a Successful Sale Actually Means
Before discussing a listing price, clarify your objective. Are you retiring, freeing capital for another purchase, reducing management responsibilities, resolving an estate, or relocating your business? The reason for selling affects the terms you should pursue.
An owner planning to reinvest may need time to coordinate another transaction. A business owner selling an occupied building may need temporary continued occupancy. Family members handling inherited property may prioritize a manageable process and a dependable closing. An investor might accept a longer marketing period to seek stronger pricing.
These goals do not automatically align. The highest potential price, fastest closing, fewest contingencies, and most flexible possession arrangement may come from different buyers. Identify your priorities before offers arrive, when there is less pressure to make quick decisions.
Ownership authority also needs attention. Confirm who holds title and who can approve the sale. If the property belongs to an entity, an estate, or several partners, have counsel review the required approvals and signing authority. A disagreement discovered after negotiations begin can interrupt an otherwise workable transaction.
Discuss the mortgage early. Request information about payoff requirements, prepayment provisions, release procedures, and other secured obligations. A favorable offer can look less attractive after unexpected loan costs enter the calculation. Your broker needs the property strategy; your attorney and accountant need the ownership and financial structure.
Define your desired net proceeds, acceptable timing, and essential terms together. This gives the sale a clear destination. Without that framework, owners can spend months pursuing an impressive asking price that does little to advance their actual financial or business goals.
Identify the Right Buyer for Your Commercial Property
Commercial buyers purchase different outcomes. Some want income. Some need space for their business. Others see an opportunity to renovate, reposition, or redevelop. A strong marketing plan identifies which of those motivations best fits the property.
An investor purchasing an occupied mixed-use building will examine rent collections, leases, expenses, tenant stability, and future capital needs. Attractive finishes help the presentation, but dependable cash flow and understandable operating responsibilities usually matter much more to that buyer’s analysis.
An owner-user approaches the building differently. A dentist, contractor, professional practice, retailer, or service company may focus on layout, customer access, equipment requirements, parking, and occupancy timing. Existing tenants can provide income while also limiting the space available to that buyer.
A developer will look at site dimensions, municipal requirements, access, environmental conditions, and approval risk. Any potential project must be investigated. A concept drawing or neighboring development does not establish that the same use, density, or design will be permitted on your parcel.
Some properties appeal to several buyer categories. That can broaden exposure, but the sales materials should distinguish the relevant cases. An income investor needs a financial presentation. A business owner needs usable-space information. A developer needs documented site and zoning facts, with unapproved possibilities clearly identified.
Trying to market every property to everyone often produces vague advertising. The stronger question is: who has a compelling, financially credible reason to own this specific building? Answer that question first, then choose the channels and information most likely to bring those buyers into a serious conversation.
Build a Defensible Valuation
Your asking price should reflect how buyers evaluate the asset. Depending on the property, that may involve comparable sales, income analysis, owner-user alternatives, land value, or several approaches considered together. No single shortcut fits every commercial building.
Comparable sales require careful selection. Another Essex County property may have a similar size yet very different leases, parking, condition, location, or tenant credit. A price per square foot can provide context, but only when those differences are understood and addressed.
The income approach asks what the property’s operating income can support at an appropriate return requirement. That involves net operating income, commonly called NOI, and a capitalization rate informed by comparable investment evidence and asset-specific risk. A cap rate is an analytical input, not a universal countywide constant.
Owner-user value may differ from investor value. A business purchasing a building for its own use may compare ownership costs against leasing alternatives and relocation expenses. A vacant property that produces no current income can still have value, although financing and adaptation costs remain central.
Replacement cost can provide additional perspective, especially for specialized improvements. However, money spent constructing or renovating a building does not automatically translate into an equal resale premium. Buyers evaluate whether those improvements benefit their intended use and whether competing properties offer a better alternative.
Request a valuation that explains its assumptions. You should understand the relevant comparables, expense adjustments, income estimates, and risks affecting the range. A number without reasoning is difficult to defend when a buyer, lender, or appraiser begins asking questions. Confidence comes from evidence, not volume.
Get the Income and Expenses Right
For income-producing commercial property, the financial package is part of the product. Buyers need a current rent roll, executed leases, amendments, collection history, and operating statements that make the property’s performance understandable.
A rent roll should identify each tenant, occupied space, base rent, lease dates, security deposit, and material financial responsibilities. Include renewals, concessions, reimbursements, and arrears where relevant. Distinguish rent that is contractually due from rent that has actually been collected.
Operating statements should separate property operations from financing and ownership-specific items. Mortgage payments, depreciation, and an owner’s personal expenses do not belong in a conventional NOI calculation. At the same time, recurring costs should not disappear simply because the owner handles them informally.
Property taxes, insurance, repairs, utilities, management, and other operating expenses need appropriate treatment. Reimbursements should be presented consistently with the expenses they offset. Major capital expenditures generally require separate disclosure and consideration even when excluded from conventional NOI.
Consider a hypothetical property with $180,000 in effective annual operating income and $60,000 in operating expenses. Its NOI would be $120,000 before debt service and other excluded items. At an assumed 7.5% capitalization rate, that income indicates $1.6 million in value. At an assumed 8.5%, it indicates roughly $1.41 million.
Those rates and figures are illustrative, not Essex County market benchmarks. The example shows why accurate income and reasonable return assumptions matter. Small changes can materially affect indicated value. Clean financials help buyers evaluate the asset; inflated figures invite a later price reduction when due diligence reveals the difference.
Present Potential Income Without Disguising Uncertainty
Many owners believe their building can generate more income than it currently produces. They may be right. Below-market leases, vacant space, or operational inefficiencies can create an opportunity. The important question is how much effort, cost, time, and risk stand between today’s performance and that future result.
Present actual operations separately from a projected scenario. State the assumptions behind proposed rents, occupancy, expenses, and improvements. If comparable leasing evidence supports the projection, include it. If a change depends on lease expiration or tenant turnover, make that timing visible.
A vacant storefront may rent at an attractive level after improvements. The buyer still needs to consider downtime, leasing costs, concessions, and construction. A projection that assumes immediate occupancy without those costs creates an unrealistic picture and weakens the credibility of the offering.
The same applies to an owner who has never charged management fees because they personally operate the property. A buyer may need professional management or assign a cost to their own time. Explain the historical operation while allowing realistic underwriting of the next owner’s expenses.
Potential value can support a compelling marketing story when the path is documented. It becomes less convincing when the presentation asks buyers to pay today for work they must finance tomorrow. Buyers generally expect compensation for taking uncertainty and execution risk.
Your strongest position is transparency: this is what the building earns, this is what may improve, and these are the assumptions and costs involved. That approach makes the opportunity easier to evaluate and helps distinguish a credible upside case from an optimistic spreadsheet.
Review Leases Before the Property Goes to Market
A commercial lease can strengthen value or create obstacles. Its impact goes beyond the monthly rent. Buyers will examine the remaining term, renewal rights, expense obligations, assignment provisions, termination options, and other language that shapes future ownership.
A dependable tenant with a clear lease may support investor interest. The same lease may reduce interest from an owner-user who needs the space soon. A short remaining term can create flexibility while introducing renewal and vacancy risk. Neither situation is automatically good or bad; it depends on the buyer.
Locate every lease and amendment. Resolve missing signatures and unexplained discrepancies with counsel where possible. If the owner and tenant have made informal arrangements about parking, storage, repairs, or rent, determine how those arrangements should be documented and disclosed.
Security deposits deserve their own reconciliation. Confirm amounts held, how they are maintained, and the obligations for transfer or credit at closing. Tenant arrears, disputes, prepaid rent, and outstanding landlord obligations should also be identified before negotiations advance.
Buyers and lenders may request tenant estoppel certificates confirming specified lease facts. Plan for that process early, including who will communicate with tenants and what cooperation the leases require. Last-minute document requests can create avoidable delays when tenants are unavailable or concerned.
Avoid signing a new lease simply to make the rent roll appear stronger. A below-market agreement, generous option, or occupancy commitment may constrain the sale. Evaluate prospective leasing decisions against the target buyer and expected disposition strategy, with legal advice on the actual terms.
Prepare the Building to Withstand Scrutiny
Presentation matters, but commercial preparation should prioritize function, safety, documentation, and foreseeable capital costs. A buyer wants to know what works, what needs attention, and what ownership will require after closing.
Review the roof, mechanical equipment, electrical service, plumbing, drainage, and visible structural conditions. Gather service records, warranties, permits, and information about significant repairs. When a system is nearing replacement, obtain realistic professional guidance rather than hoping the issue will escape notice.
Basic improvements can help. Clean common areas, remove unnecessary stored items, improve lighting, maintain landscaping, and make vacant spaces accessible for inspections. Clear circulation and orderly service areas help buyers understand the property and create a more professional impression.
Do not renovate extensively without considering the likely purchaser. Specialized finishes may have little value to a buyer planning a different use. Money spent addressing a documented maintenance problem can be more useful than an expensive cosmetic project that the next owner will remove.
Evaluate accessibility and life-safety questions with qualified professionals where relevant. The requirements can depend on the building, existing use, proposed changes, and applicable rules. Avoid assuring buyers that a property meets every requirement without supporting documentation and appropriate expertise.
Preparation is about reducing uncertainty responsibly. You do not have to deliver a flawless building, but you should understand its condition and present it honestly. An informed seller can discuss a defect with context. An uninformed seller is more vulnerable when a buyer turns that defect into a broad argument for repricing.
Verify Zoning, Occupancy, and Parking Facts
One of the most expensive mistakes in commercial marketing is treating a possible use as an approved use. Essex County municipalities have their own ordinances and procedures. Requirements can vary by district, parcel, existing approvals, and the proposed activity.
Confirm the property’s zoning designation and locate available approvals, certificates, permits, and relevant municipal records. Ask the appropriate local officials and professionals about material questions. If the buyer intends a new use, identify the need for their own investigation rather than supplying an unsupported assurance.
Mixed-use buildings require particular attention. Verify the number and status of residential units, commercial occupancies, and any conversion work. A room used as an apartment is not proof of a legally authorized dwelling. Discrepancies can affect financing, insurance, valuation, and closing requirements.
Parking is equally important. Distinguish owned parking from leased spaces, shared arrangements, easements, and public parking. Count the spaces carefully and describe restrictions. Nearby municipal parking can help some businesses, but it does not create an ownership right or guaranteed availability.
For retail or restaurant prospects, investigate practical matters such as deliveries, ventilation, refuse storage, signage, and required approvals. For industrial users, loading and vehicle circulation may be decisive. A use that sounds suitable in an advertisement may fail when these details are examined.
Accurate information helps the right buyer move forward. It also filters out buyers whose plans are unlikely to work. That is useful marketing discipline. A large volume of inquiries means little when most prospects need a use, layout, or approval the property cannot realistically provide.
Address Environmental Questions Early
Environmental due diligence deserves attention before an offer becomes a deadline. Prior uses, neighboring conditions, underground tanks, chemical storage, and other history can raise questions even when the current business appears uncomplicated.
The EPA describes All Appropriate Inquiries as an evaluation of environmental conditions and potential contamination liability. A properly scoped Phase I environmental site assessment can support that process under recognized standards. It does not mean every environmental risk has been eliminated or that no further investigation will be needed. US EPA
Collect existing assessments, tank records, remediation documents, and agency correspondence. Discuss their relevance and age with an environmental professional. A report prepared for an earlier owner or lender may not satisfy a new purchaser’s current requirements or provide the necessary reliance rights.
New Jersey’s Industrial Site Recovery Act, or ISRA, can impose obligations on qualifying industrial establishments when specified ownership or operational events occur. Applicability depends on defined criteria, including business classification and hazardous-substance activity. The state identifies potential compliance triggers such as signing an agreement to sell a qualifying property. ISRA Applicability
Have counsel and an environmental professional evaluate applicability before you assume the law does or does not apply. Some situations involve a Licensed Site Remediation Professional and particular compliance procedures. The appropriate path depends on the property’s actual history, operation, and transaction structure. ISRA Applicability
An environmental issue does not necessarily prevent a sale, but it can change pricing, financing, timing, and contractual responsibilities. Documented information allows the parties to evaluate a workable solution. Silence or vague reassurance usually makes the eventual discovery harder to manage and can undermine trust in the rest of the seller’s information.
Create Marketing That Answers Business Questions
Commercial marketing should make the property easier to understand and evaluate. Professional photographs are useful, but they work best alongside reliable facts, floor plans, financial information, and a clear explanation of the opportunity.
Show the features relevant to the target buyer. Retail prospects need to see frontage, entrances, customer access, and the surrounding setting. Office users need circulation, rooms, common areas, and parking. Industrial buyers need loading areas, clearances, service capacity, and operational access verified for the property.
An offering package can include an overview, location information, space details, lease summary, historical operations, capital improvements, and known issues. Clearly label approximate measurements and projections. Include the information necessary for an initial decision without exposing sensitive tenant or business data unnecessarily.
Marketing copy should explain why the building deserves attention. “Great investment” says almost nothing. A description of the tenant mix, lease structure, documented income, and specific location advantages gives an investor reasons to investigate. The evidence should carry the argument.
Use a controlled process for confidential information. Preliminary materials can attract interest, while detailed documents may be released to appropriate prospects under agreed procedures. Coordinate that process with counsel where needed, especially when the sale involves an operating business or sensitive financial records.
Distribution should match the buyer. Commercial listing channels, direct broker outreach, investor relationships, and targeted communication with potential users may all have a role. The marketing plan should explain who it intends to reach and how success will be measured beyond impressions or clicks.
Balance Exposure With Confidentiality
Some owners want broad public exposure. Others worry that employees, tenants, customers, or competitors will learn about the sale. Both concerns are legitimate, and the strategy should reflect the property and business circumstances.
Public marketing can expand discovery and make it easier for brokers and buyers to find the opportunity. A discreet approach may reduce disruption, particularly when an operating company remains in place. However, reduced exposure can also limit competition. The tradeoff should be understood before selecting a method.
Separate the real estate sale from any proposed business sale. They involve different assets, information, valuation questions, and potential buyers. Equipment, inventory, licenses, customer relationships, and business goodwill should not be casually included in a building offering without an explicit plan and professional advice.
Establish showing rules that protect operations. Decide how much notice is required, which areas are accessible, and who will accompany prospects. For occupied properties, respect the leases and coordinate access properly. Surprise visits can damage tenant relationships and create unnecessary resistance.
A confidentiality agreement can support controlled disclosure, but it is only part of the process. Limit the information shared to what is appropriate at each stage. Remove unnecessary personal details and use organized access rather than sending unrestricted folders to every person who asks.
Confidentiality and effective marketing can coexist when the process is deliberate. The objective is to let credible buyers evaluate the opportunity while minimizing avoidable disruption. That requires planning, clear communication, and consistent handling of inquiries from the first advertisement through the final inspection.
Understand How Financing Affects the Sale
An interested buyer is not yet a financed buyer. Commercial lending evaluates both the borrower and the property. Income, collateral, borrower experience, equity, tenant quality, condition, and intended use can influence the lender’s decision.
Discuss the proposed financing early. Ask about the lender relationship, expected equity contribution, loan structure, and underwriting milestones. A buyer who has reviewed the transaction with a suitable lender is in a different position from someone who assumes a residential-style approval will carry over.
Income properties may be assessed using debt service coverage alongside other factors. The lender wants to understand whether property income reasonably supports the proposed debt payments. Exact requirements vary, so avoid relying on one ratio or treating an online estimate as a commitment.
Owner-user transactions present their own questions. A business may need funds for renovations, equipment, working capital, and relocation in addition to the purchase. That total project cost can influence how much the purchaser can pay for the building and whether the proposed closing schedule is realistic.
Interest rates can affect purchasing power, but commercial pricing cannot be reduced to a single rate headline. Loan terms, amortization, reserves, tenant risk, and borrower circumstances also matter. Evaluate the buyer’s actual financing path rather than assuming every prospect faces identical constraints.
Financing risk should shape negotiations. Ask what remains unresolved, how long the lender needs, and what documents must be provided. A credible financing plan supports a more dependable transaction. Vague assurances about obtaining a loan deserve careful follow-up before the seller commits valuable time and removes the property from active marketing.
Compare Offers by Their Likelihood of Closing
The purchase price is only one part of an offer. Review the deposit, financing contingency, inspection rights, approval conditions, requested credits, assignment provisions, closing schedule, and possession terms with your broker and attorney.
Consider a hypothetical $1.8 million offer with a lengthy investigation period and several unresolved approvals. A $1.72 million offer with stronger equity and a clearer path to closing may be more attractive, depending on the facts. The difference in price must be weighed against execution risk and carrying costs.
Ask for reasonable evidence of purchasing capacity. Verify whether the buyer is purchasing directly, through an entity, or with partners. Understand who will authorize the transaction and supply the funds. A polished presentation does not substitute for a workable financial structure.
Review redevelopment contingencies carefully. A buyer may need municipal approval before closing, potentially tying up the property for an extended period. Consider deadlines, extension terms, deposits, and the allocation of risk with counsel. The seller should understand what happens if the project never receives approval.
Seller financing can sometimes help bridge a transaction, but it changes the seller’s role and risk. Evaluate security, priority, repayment, borrower strength, enforcement, and tax consequences before agreeing. A deferred payment is not equivalent to receiving cash at closing.
The best offer is the one that best serves your objectives with an acceptable probability of performance. That judgment requires detail. Negotiating only the headline number can leave an owner with attractive paperwork, prolonged uncertainty, and a property that eventually returns to market under less favorable circumstances.
Manage Due Diligence With Organized Information
Once a contract is signed, the buyer’s investigation becomes the focus. The parties will review documents, inspect the building, address financing requirements, and work through title and other conditions. Preparation before listing can shorten the time spent hunting for basic information.
Create a structured document collection with leases, rent rolls, operating statements, service records, surveys, permits, environmental materials, insurance information, and applicable approvals. Label documents accurately and identify missing items. Organization makes requests easier to track and reduces contradictory answers.
Maintain a clear request log. Record what the buyer requested, who is responsible, when it was provided, and what remains outstanding. Your attorney should manage legal responses and deadlines, while your broker helps coordinate commercial questions and access.
Schedule inspections with tenants and operators in mind. Coordinate roof access, mechanical rooms, occupied spaces, and any testing that requires special arrangements. Buyers and their professionals need meaningful access, but that access should follow the contract and applicable occupancy rights.
Expect underwriting questions. A buyer may ask why expenses changed, why a tenant received concessions, or how a proposed repair estimate was prepared. Accurate explanations with supporting records are more effective than defensiveness. The goal is to resolve legitimate uncertainty without accepting unsupported conclusions.
Not every inspection finding justifies a price reduction. Review the issue, its significance, the contract, and reasonable cost evidence. An organized seller can respond proportionately. When the building’s information is incomplete, even modest findings can become the starting point for a broader and more expensive renegotiation.
Calculate Net Proceeds Using Current Rules
Your sale price is not the amount you keep. Estimate proceeds after mortgage payoff, loan charges, brokerage compensation, legal expenses, transfer fees, agreed credits, prorations, and other transaction-specific costs. Have your accountant address income-tax consequences separately.
New Jersey imposes a Realty Transfer Fee on sellers, subject to applicable exemptions. Certain property transfers above $1 million also incur a supplemental Graduated Percent Fee. The state identifies Class 4A commercial property among the covered classifications, while its listed Class 4A category excludes industrial and apartment property. Classification must be verified. Property Sale Realty Transfer Fee
For covered transfers, published graduated rates range from 1% to 3.5% of total consideration, depending on the sale-price band. The seller is statutorily responsible. The rate applies to total consideration, rather than only the portion above the threshold. These details can materially change an owner’s estimate of proceeds. Property Sale Realty Transfer Fee
For illustration, an applicable $2.2 million transaction falls within the published 2% band, producing a $44,000 Graduated Percent Fee before the regular Realty Transfer Fee and other expenses. Counsel should confirm the applicable classification, consideration, exemptions, and current treatment for the particular transaction. Property Sale Realty Transfer Fee
Selling an ownership interest in an entity is not automatically a way around transfer taxation. New Jersey also describes a seller-imposed Controlling Interest Transfer Tax on certain transfers involving entities that own qualifying commercial property. Its applicability depends on the transaction and statutory requirements. nj.gov
Request a preliminary closing-cost estimate before selecting a price and refresh it when terms change. This helps compare offers on the basis that actually matters: the expected financial result. A strong headline price can conceal substantial costs when the net calculation is postponed until closing.
Plan for Taxes and Possible Reinvestment Before Closing
The tax consequences of a commercial sale depend on your circumstances. Basis, depreciation, ownership structure, improvements, and the nature of the transaction can affect the result. Your accountant should review those facts before you make commitments about reinvesting or distributing the proceeds.
A Section 1031 exchange may allow qualifying investment or business real estate to be exchanged with recognition of gain deferred when the requirements are met. It is a specific transaction structure, not simply selling a property and later buying another one. Internal Revenue Service
The IRS explains that actual or constructive receipt of proceeds can prevent the intended treatment. Qualified intermediary arrangements are one recognized way of handling a properly structured exchange. Discuss the process with appropriate tax, legal, and exchange professionals before the sale closes. Internal Revenue Service
For deferred exchanges, IRS instructions generally require identifying replacement property within 45 days of transferring the relinquished property. Receipt of replacement property must occur within 180 days or by the applicable tax-return due date, including extensions, whichever comes earlier. Those timelines create real planning demands. Internal Revenue Service
Do not purchase an unsuitable replacement asset solely to meet a deadline. Evaluate cash flow, physical condition, financing, management demands, and long-term fit. Tax deferral can be valuable, but it does not turn a weak investment into a sound one.
If your priority is retirement, debt reduction, or simplifying ownership, compare the alternatives with your advisers. The right exit strategy should serve your broader goals. Closing the sale is one milestone; deciding what the proceeds should accomplish is the larger financial decision.
Choose Representation With a Clear Commercial Plan
Commercial property owners should expect a specific explanation of how their building will be valued, presented, marketed, and managed through the transaction. Ask prospective brokers to discuss the likely buyer and the evidence supporting their strategy.
A useful conversation covers comparable transactions, financial preparation, required materials, exposure channels, buyer qualification, confidentiality, and foreseeable obstacles. Ask who will handle inquiries and how feedback will be reported. The answers should relate directly to your property rather than a generic sales pitch.
Communication matters throughout the process. Agree on how often you will review activity and which indicators will guide decisions. Inquiries, document requests, second visits, financing discussions, and offers provide more useful information when considered together than a raw count of online views.
If activity is weak, investigate the cause. The problem may be pricing, incomplete documentation, unsuitable marketing, condition, or a mismatch between the offering and available buyers. A responsible adjustment should follow evidence. Repeating the same advertisement does not resolve an underwriting problem.
Build the right professional team. A broker coordinates the market strategy, while attorneys, accountants, lenders, engineers, and environmental professionals address their respective areas. Specialized questions should receive specialized answers. Clear responsibilities help prevent assumptions from becoming contractual problems.
Selling your commercial property in Essex County starts with understanding what you own and what the next buyer needs. Accurate pricing attracts credible attention. Reliable documentation supports underwriting. Targeted marketing explains the opportunity. Disciplined negotiation protects your objectives through closing.
If you are considering selling a storefront, office building, mixed-use property, warehouse, or other commercial asset in Essex County, contact Matthew De Fede at Realty Executives Elite Homes. Start with a conversation about the property, your goals, and the information needed to build a practical selling strategy.
Matthew De Fede
Broker/Owner | Realty Executives Elite Homes
www.matthewdefede.com